If you’ve received a collision repair estimate, you may have noticed a charge labeled “betterment.” This insurance adjustment can leave you responsible for part of a replacement part’s cost, even when an accident caused the damage.
Betterment in car insurance generally refers to the increased value or useful life a vehicle receives when a worn part is replaced with a new one. Tires and batteries are common examples.
Understanding how betterment works can help you review your repair estimate, identify potential out-of-pocket costs, and ask your insurance adjuster the right questions.
What Does Betterment Mean in Car Insurance?
Betterment means a repair leaves a specific part in a measurably improved condition compared with its condition just before the collision.
Suppose a three-year-old battery is damaged during a covered collision and requires replacement. The original battery had already provided part of its expected service life. A new battery starts with a full service life. The insurer may calculate the difference as betterment and assign part of the battery cost to the vehicle owner.
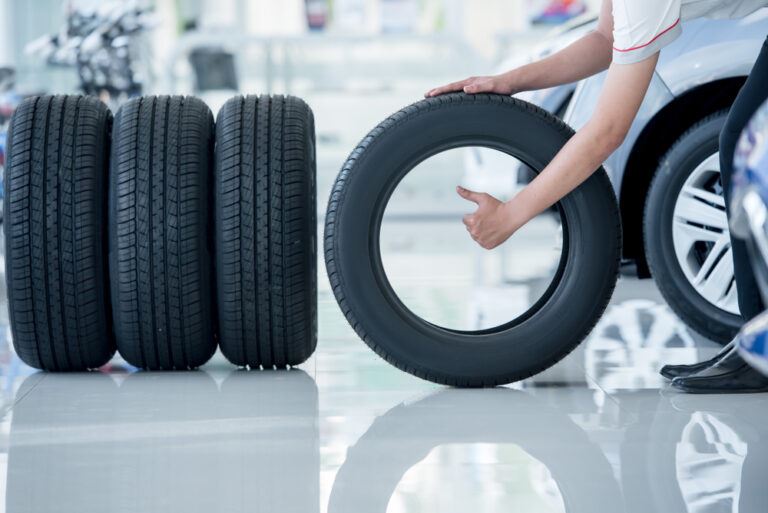
The same idea can apply to a worn tire. If a collision damages a tire that had already used a measurable amount of its tread, the new tire gives the vehicle more usable tread than it had before the loss.
Betterment focuses on that added value or service life. It should connect to the age and condition of the specific part rather than serve as a general reduction to the claim.
A detailed collision repair estimate helps separate the full repair cost from the insurer’s payment adjustments. This gives you a clearer view of the work being performed and the amount assigned to each party.
What Do California Claim Rules Require for Betterment?
California Code of Regulations, Title 10, §2695.8 sets standards for betterment and depreciation adjustments in automobile claims.
When an insurer adjusts a claim for betterment, the justification belongs in the claim file. The adjustment must be discernible, measurable, itemized, and stated as a specific dollar amount. The insurer must explain the basis for the adjustment to the claimant in writing.
The calculation should reflect a measurable difference in market value tied to the part’s age and condition. It applies to parts that normally require repair or replacement during the useful life of a vehicle. Tires and batteries are listed as examples.
Labor receives separate treatment in a first-party partial-loss claim. The expense of labor needed to repair or replace the damaged item is generally outside a betterment or depreciation adjustment unless the insurance contract contains clear language permitting it.
These standards give you practical questions to ask when a charge appears:
- Which part received the adjustment?
- What condition or age information supports it?
- How was the percentage calculated?
- What dollar amount does the percentage represent?
- Does the adjustment apply to the part, labor, or both?
- Where is the written explanation?
The answers should connect the calculation to the part on your vehicle and the terms of the claim.
Which Car Parts May Receive a Betterment Adjustment?
Betterment most often involves parts with a measurable service life. Their age, wear, or remaining use can be documented before replacement.
Tires
Tires gradually use their available tread. An insurer may compare the damaged tire’s tread depth with the tread depth of the replacement tire.
The calculation may consider the amount of usable tread that remained before the collision. A tire with substantial remaining tread would usually have a smaller adjustment than a tire near the end of its service life.
Tire type also matters. Size, brand, performance rating, load rating, and vehicle requirements can affect the replacement selected for the repair.
Batteries
Batteries have an expected service period that can vary with type, age, climate, vehicle use, and condition.
If a covered collision damages an older battery, the insurer may compare its age and remaining useful life with the full life of the replacement battery. The betterment percentage may reflect the service life added by the new part.
Other Wear Items
Other parts may qualify when the insurer can document a normal useful life and a measurable improvement in value. The part and calculation should satisfy the same itemization and explanation requirements.
A collision may involve mechanical components that already showed measurable wear. The insurer may review their pre-loss condition before deciding whether a betterment adjustment applies.
Body panels, structural components, lamps, sensors, and similar collision parts serve a different purpose from routine wear items. Any betterment applied to a particular part should come with a clear explanation of the measurable improvement.
How Is a Betterment Charge Calculated?
The insurer generally compares the replaced part’s remaining value or useful life with the full value or useful life of the new part.
Here is a simple illustration:
- Replacement part price: $250
- Estimated portion of useful life already used: 60%
- Betterment adjustment: $150
- Insurer’s remaining part allowance before other claim adjustments: $100
In this example, the insurer assigns 60% of the new part’s price to betterment because the replacement adds that portion of service life. The actual formula may use age, mileage, tread measurements, condition, warranty information, or another documented factor appropriate to the part.
The percentage and dollar amount should both appear clearly. A written explanation should show how the insurer reached the result.
The repair facility may provide measurements or condition information during the estimate process. The insurer applies its policy and claim calculation to determine the adjustment.
Where Does Betterment Appear on a Repair Estimate?
Betterment may appear near the affected part, in the claim-summary section, or in the payment breakdown. The wording varies among estimating and insurer systems.
Common labels include:
- Betterment
- Betterment adjustment
- Depreciation
- Owner responsibility
- Customer pay
- Prior wear adjustment
The estimate may show the full replacement price first and then subtract the betterment amount from the insurer’s share.
| Estimate entry | Example amount | What it means |
| New wear item | $250 | Full price of the replacement part |
| Betterment adjustment | $150 | Amount assigned to the added service life |
| Insurer part allowance | $100 | Remaining part amount before other policy adjustments |
| Customer betterment portion | $150 | Amount connected with the betterment calculation |
This example covers only the part price. Labor, taxes, materials, the policy deductible, and other estimate lines may appear separately.
Our estimate process identifies the operations and parts needed for the repair. If the insurer’s estimate includes betterment, compare the two documents line by line. The repair total may remain the same while the payment allocation changes.
Is Betterment the Same as a Deductible?
Betterment and a deductible are separate amounts.
Your deductible comes from the insurance policy. It is the amount you agreed to pay toward a covered claim before the insurer’s payment applies.
Betterment relates to the added value or useful life created when a worn part is replaced with a new one. It applies only when the insurer supports a measurable adjustment for the specific part.
A repair estimate can include both amounts. For example, you may have a $500 deductible and a $150 betterment adjustment for a tire. The payment summary may assign $650 to you before any other approved customer-pay items.
Keeping the two charges separate helps you review them accurately:
- Deductible: Set by the policy
- Betterment: Calculated from the affected part’s pre-loss age or condition
Ask the insurer to identify each amount and show how it entered the payment calculation.
Is Betterment the Same as Depreciation?
The terms are related, and estimate systems sometimes use them in similar ways.
Depreciation describes a reduction in value over time because of age, use, or condition. Betterment describes the measurable improvement created by replacing an older or worn part with a new one.
In a collision estimate, the practical result may be a reduction in the insurer’s payment for that specific part. The written explanation should identify the calculation and the reason behind it.
The label matters less than the supporting information. You should be able to see the part, its replacement cost, the percentage or amount applied, and the basis for the adjustment.
Who Decides Whether Betterment Applies?
The insurer applies the betterment adjustment under the policy and claim rules. The repair facility identifies the damage, prepares the repair plan, and provides supporting information related to the vehicle and affected parts.
At Network Auto Body, we can help you locate the charge on the estimate and understand how it affects the repair balance. Questions about the insurer’s percentage, policy basis, or payment decision belong with the adjuster.
During vehicle disassembly and repair planning, we may find damage or wear that was hidden during the first inspection. We document what we find and update the estimate when the collision requires additional work.
A supplement can change the repair total and the insurer’s payment breakdown. If a newly identified part receives betterment, the insurer should itemize and explain that additional adjustment.
What Should You Review Before Authorizing the Repair?
Start with the complete estimate and payment summary. Find the part receiving betterment and confirm that the adjustment appears as a separate line or clearly identified amount.
Then review:
- The affected part: Confirm which tire, battery, or other wear item received the adjustment.
- Pre-loss condition: Ask which measurement, age, mileage, or condition rating the insurer used.
- The calculation: Request the percentage, dollar amount, and formula.
- Parts and labor: Confirm which portion of the repair received the adjustment.
- Policy language: Ask the adjuster which policy provision supports the charge.
- Supporting records: Provide receipts, warranty information, service records, or recent replacement documents that may affect the calculation.
- Payment allocation: Confirm the insurer’s share, your deductible, the betterment amount, and any other customer-pay items.
For example, a receipt showing that a battery was installed six months before the collision may change the age information used in the calculation. A tire invoice may confirm its installation date, specifications, or warranty coverage.
Clear documentation gives the adjuster specific information to review.
Review Your Collision Repair Estimate With Us
A betterment charge becomes easier to understand when the estimate identifies the affected part, replacement price, adjustment percentage, dollar amount, and payment allocation.
At Network Auto Body, we prepare detailed repair estimates, document collision-related damage, and communicate with insurers as the repair plan develops. We can walk you through the repair lines and show you where betterment, the deductible, and other payment amounts appear.
If you have questions about the insurer’s calculation, you can ask the adjuster for the written basis and supporting measurements. We will continue focusing on the parts, procedures, and repair operations required for your vehicle.
If betterment appears on your repair estimate, contact one of our five Southern California auto body shop locations in Downtown Los Angeles, North Hollywood, Van Nuys, Valencia, or Oxnard to review the repair plan and learn more about the parts and procedures relevant to your vehicle.